
Watch Loans
How to Pawn a Rolex in Australia: What to Know Before You Borrow Against It
What a pawn loan on a Rolex legally is, what the pawnbroker checks before advancing, the full cost stated once, what the pawn ticket must contain, how redemption and extension work, and what happens if you cannot repay, under Victorian law.
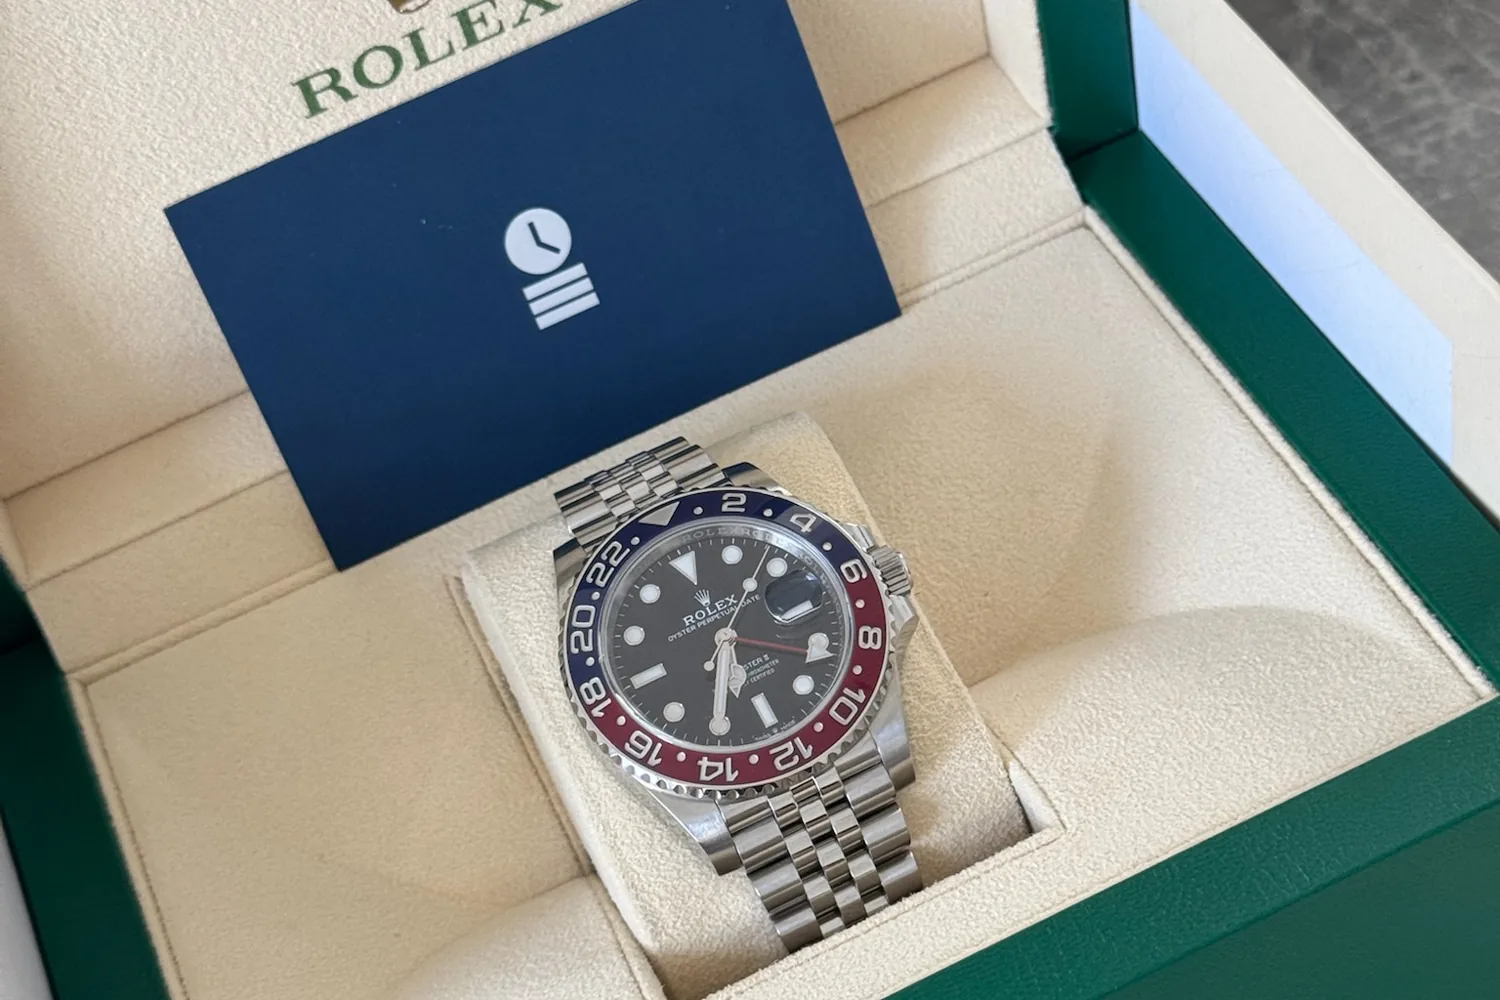
The short answer: pawning a Rolex means handing it to a licensed pawnbroker as the only security for a fixed-term loan, and taking it back the day the loan is repaid. You keep ownership throughout. The pawnbroker inspects the watch the same way a buyer would, sets the advance against what it would realise if sold, gives you a pawn ticket and a written statement of the charges, stores the watch insured, and if the loan is not repaid sells the watch and has no further claim on you. Before you sign, know the reference you are pawning, what the loan costs in full, what the ticket must say, and how to check the pawnbroker is registered.
Summary
A Rolex is the watch most often pawned in Australia, because it holds value, it is easy for a pawnbroker to authenticate and sell, and most owners would rather borrow against one than lose it. That also makes it the watch where a borrower most needs to understand the mechanics: the advance depends on reference, condition and documents just as an offer to buy does, the cost is high by the standards of ordinary consumer credit and is lawful for reasons worth understanding, and the protections you have are specific and written into Victorian law. This guide sets all of that out in the order it happens. Buy Your Watch lends against Rolexes under a Victorian pawnbroker licence, so the commercial interest is obvious and disclosed; every claim here is checkable against the sources at the end whoever you borrow from.
Key takeaways
- You stay the owner. A pawn loan is a loan secured on the watch, not a sale with an option to buy back, and the difference is written into the Second-Hand Dealers and Pawnbrokers Act 1989 (Vic).
- The pawnbroker will inspect and authenticate your Rolex exactly as a buyer would, and will ask for your identification because section 19 of the Act requires it.
- You must be given a pawn ticket, a written notice of the charges and the "What are my rights when I pawn goods?" notice. Read the ticket: the law says what it must contain.
- At Buy Your Watch the cost is stated once and completely: a minimum advance of $15,000, terms of 3 to 12 months, a $400 setup fee, interest of 4% to 10% per month depending on assessment, and a maximum annual percentage rate of 131%.
- The watch is the pawnbroker's only recourse. If you cannot repay, the watch is sold at the best price reasonably obtainable, you owe nothing further, your credit file is untouched, and any surplus over the debt is yours to claim for 12 months.
- A pawn loan sits outside the National Credit Code's 48% cap by a specific exemption, but the Code's power for a court to reopen an unjust transaction still applies to it.
Who this guide is for
An Australian who owns a Rolex outright, needs money for a defined period, and expects to want the watch back. It assumes you have the watch in hand. It does not give a figure for what a particular Rolex will borrow, because that depends on the watch in front of the pawnbroker, and it does not compare lenders on rate, for a reason explained below.
How this guide was prepared
The legal position is Victorian, because Buy Your Watch holds its pawnbroker licence in Victoria, and each statutory claim names the section or regulation it comes from, checked against the Act, the 2018 Regulations and Consumer Affairs Victoria's published guidance on 15 September 2026. The cost figures are Buy Your Watch's own published terms. Nothing here is legal or financial advice, and other states run their own Acts with their own numbering.
Understand what a pawn loan on a Rolex legally is
In Victoria a pawnbroker is a person who lends money on the security of pawned goods, and the Act regulates the whole transaction: who may do it, what they must record, what they must give you, how long they must hold the goods, what happens when the loan ends and what you are owed if the goods are sold. [1] Three features define the arrangement and separate it from every other way of raising money on a watch.
- Ownership does not move. The watch is security for the loan. It is not sold to the pawnbroker, and a pawnbroker cannot simply keep it if the loan is not repaid: the Act requires an unredeemed watch to be offered for sale, and the borrower keeps a claim on the proceeds. [4] [5]
- The watch is the only recourse. Under section 6(9) of the National Credit Code, credit provided by a pawnbroker in the ordinary course of a lawfully conducted pawnbroking business is outside the Code, on the condition that if the borrower defaults the pawnbroker's only recourse is against the goods. [9] That condition is why a pawnbroker cannot pursue you for a shortfall, and it is also why the Code's 48% annual cost cap in section 32A does not apply. A pawnbroker who claimed a right to chase you for the balance would be outside the exemption and inside the cap. The two go together.
- Some consumer credit protection still reaches it. The same section 6(9) preserves sections 76 to 81 of the Code, which allow a court to reopen an unjust transaction. [9] The exemption removes the cap, not the court.
Two things sometimes offered as "the same as a pawn loan" are not. A sale with a right to buy the watch back is a sale: ownership passes, the price you buy back at is whatever the contract says, and none of the Act's borrower protections apply. A personal loan secured over a watch by a licensed credit provider is inside the Code, capped at 48%, and the lender can pursue you for any shortfall. Our guide to what happens if you cannot repay a watch loan works through the difference in detail.
Check who can lawfully take a Rolex in pawn
Section 5 of the Act makes it an offence to carry on business as a pawnbroker without being registered. [2] Registration is with Consumer Affairs Victoria, the register is public, and every registered pawnbroker has a number. Buy Your Watch's is SHD-0017882. Before you hand over a Rolex, look the number up and check the business name on the register matches the name on the paperwork and on the bank account that will pay you. A pawnbroker must also display its registration certificate and its notice of charges at the premises. [6]
If the person offering to lend against your watch cannot give you a registration number, they are not a pawnbroker, whatever they call the arrangement, and nothing in this guide protects you.
Know what the pawnbroker will check on your Rolex
A pawnbroker advances money against what the watch would realise if it had to be sold, so the inspection is the same one a buyer makes. Expect it, and prepare for it.
- The reference and serial. The reference is engraved between the lugs at 12 o'clock; the serial is on the rehaut on modern watches and between the lugs at 6 o'clock on older ones. Both will be read and recorded, because section 20 of the Act and the record-keeping regulations require the pawnbroker to record a description of the goods including any identifying number. [8] Our guide to Rolex serial and reference numbers shows where each sits.
- Authenticity. Buy Your Watch has every watch inspected by a certified watchmaker before any funds are released. A pawnbroker who advances against a Rolex without authenticating it is either taking a risk you will pay for in the rate, or is not planning to lend at all.
- Condition. Bezel, case, dial, bracelet and movement, assessed exactly as for a purchase. A Submariner with a chipped ceramic bezel or a Datejust with a stretched bracelet will realise less at sale, so it will borrow less. The checks are the ones set out in our Submariner selling guide, and they apply to every Rolex.
- Documents. The warranty card, box and service records raise what the watch would sell for and therefore what can be advanced against it. A watch-only Rolex can still be pawned; it simply borrows against a lower figure.
- Your identity and your title. Section 19 requires the pawnbroker to ask for evidence of your identity and to refuse the goods if you cannot produce it. [3] The pawnbroker also needs to be satisfied the watch is yours to pawn. A Rolex still under a finance agreement, or one you hold for someone else, is not yours to pledge, and the Act's stolen goods provisions are the reason pawnbrokers ask.
Understand how the advance is set
The advance is a proportion of what the pawnbroker judges the watch would fetch if it had to be sold at the end of the term, at the best price reasonably obtainable, less the cost of selling it. It is not the watch's insurance value, its retail price, or what you paid. The proportion is a commercial judgement about how quickly and reliably that particular Rolex sells, so a current steel sports reference with its card will borrow a higher share of its sale value than a discontinued precious-metal dress reference without papers, even where the second watch is worth more.
Buy Your Watch's minimum advance is $15,000. In practice that means the watch needs to be one that would clearly realise well above that at sale, which most modern Rolex sports references and many Datejusts and Day-Dates in precious metal do, and some older or entry references do not. If yours is borderline, send the reference and photographs and you will be told plainly, within 24 to 48 hours, whether it is a watch that can be lent against. The loan page explains the assessment.
The full cost, stated once and completely
Google's policy for lenders, and plain honesty, both require the cost of a loan to be set out in full where you can see it before you apply. Buy Your Watch's terms are these. Loans run from a minimum advance of $15,000 over terms of 3 to 12 months. A one-off setup fee of $400 covers authentication and insured storage for the term. Interest runs from 4% to 10% per month depending on the watch, the amount advanced and the assessed risk of the loan, and is paid monthly. The maximum annual percentage rate is 131%, which includes both interest and the setup fee, and applies at the highest monthly rate on the smallest advance over the shortest term. Because the setup fee is fixed, the rate works out lower on larger advances and longer terms.
Representative example: $15,000 advanced against a Rolex, over a 3-month term, at 4% per month, with the $400 setup fee. Total repayable to redeem the watch at the end of the term: approximately $17,200, an APR of approximately 59%.
Two features of how the interest works matter more than the headline rate. First, the interest is for a fixed term: the full term's interest is payable even if you redeem the watch early, so choose the term you actually need rather than the longest one offered. Second, the interest is paid monthly rather than accrued to the end, which keeps the amount needed on the redemption date to the principal and fee, and which is also what keeps your right to extend alive, as explained below. Your exact rate, the total amount repayable and the redemption date are confirmed to you in writing before any funds are released, and you are under no obligation to proceed.
You will notice this guide does not compare that cost with other lenders' rates. That is deliberate. A pawn loan is not a low-cost way to borrow money and is not presented as one. It is compared on what it is: a fixed term of 3 to 12 months, no recourse beyond the watch, no effect on your credit file, and the watch back the day you repay. If a cheaper secured or unsecured loan is available to you, it may well be the better choice, and our guide to selling your watch or borrowing against it is honest about when.
Know what you must be given, and read it
Consumer Affairs Victoria's guidance, drawn from the Act and the 2018 Regulations, sets out three documents a pawnbroker must give you, with a penalty of up to 20 penalty units for failing to. [6]
- A pawn ticket. It must show the name and address of the pawnbroker, your full name and address, the date of the loan, the amount loaned, a description of the goods pawned, the number of the pawn transaction, the pawnbroker's charge, the period of the loan, and the amounts paid and the dates of payment, updated with each payment. Check every item against what you agreed before you leave. The ticket is what you produce to redeem the watch.
- A written notice of the charges. The pawnbroker's charges must also be displayed at the premises, expressed in dollar amounts rather than percentages, with the maximum charge stated and a note that higher amounts may apply in special circumstances.
- The prescribed notice, "What are my rights when I pawn goods?" This is the Schedule 3 notice under the Regulations and it summarises the protections in this guide. Keep it with the ticket.
At Buy Your Watch these sit alongside a written loan agreement that states the rate, the term, the redemption date and the total repayable, signed before any funds are released. Read the agreement for the same things you check on the ticket: the description of the watch including its serial, the amount, the term, the charge, and the date the watch comes back.
Know what happens to your Rolex during the loan
The Act requires a pawnbroker to keep pawned goods in the form in which they were received, without disposing of them in any way, for at least seven days, and to record where the goods are stored. [7] That seven-day minimum is a floor set by law; a pawn loan for the term you agreed holds the watch for that term. At Buy Your Watch the watch is stored insured for the whole term, and the $400 setup fee is what covers that insurance. It is not worn, not displayed, and not offered for sale while the loan is on foot. Ask any pawnbroker the same three questions: where is the watch kept, is it insured for its full value, and who is the insurer.
Understand redemption, extension and the redemption date
You redeem the watch by producing the pawn ticket and proof of identity and paying what is outstanding. The Act allows redemption at any time after the seven-day minimum holding period and before the pawnbroker sells or disposes of the goods, and that includes after the loan period has expired, right up until the watch is actually sold. [7] In other words the expiry of the term does not by itself cost you the watch; the sale does.
Buy Your Watch's agreements also provide for extension one month at a time at the same rate. The right to extend is conditional on every monthly interest payment having been made when it was due, each extension moves the redemption date forward one calendar month, and each is confirmed in writing. A missed interest payment ends the right to extend, and the sale provisions apply from the redemption date. If you can see a month early that you will not be able to redeem on the date, that is the moment to speak to the pawnbroker, not the day after.
Know what happens if you cannot repay
This is set out at length in our guide to what happens if you cannot repay a watch loan in Australia; the essentials are these. Once the loan period expires and is not extended, the pawnbroker must offer the unredeemed watch for sale as soon as practicable and so as to receive the best price reasonably obtainable. [5] [7] The watch is the only security, so the debt is settled by the sale whatever the watch fetches: Buy Your Watch does not pursue you for any shortfall, and your credit file is not affected. And if the watch sells for more than the outstanding loan plus the reasonable costs of sale, section 23A gives you 12 months after the sale to claim the difference; the pawnbroker must send you a notice of the sale within 14 days and must pay the residual equity on demand within that 12 months. [4]
Put plainly: a pawnbroker in Victoria cannot keep your Rolex, cannot chase you for money after selling it, and cannot keep a surplus that is yours. Any pawnbroker whose paperwork says otherwise is describing a transaction the Act does not permit.
Verify the pawnbroker, not just the offer
- Registration number, looked up on the Consumer Affairs Victoria register. Buy Your Watch: SHD-0017882.
- ABN on ABN Lookup, matching the registered name and the paying account.
- Who authenticates the watch, and whether they are certified. Buy Your Watch uses certified watchmakers in every Australian capital city; they are partner businesses, not our premises, and we say so.
- Where the watch is stored and who insures it.
- The cost, in full, in writing, before you commit. A pawnbroker who quotes a monthly rate without the term, the fee and the annual figure is quoting you half the cost.
- Reviews with the dates showing.
Want to know what your Rolex could borrow? Send the reference, a few photographs and what documents you hold. The assessment is free, places you under no obligation, and has no effect on your credit file. Funds are released once the watch has been authenticated by our certified watchmakers, and the process takes 24 to 48 hours from submission to payment.
Decide between pawning the Rolex and selling it
Borrowing is the right route when you want the watch back and the need for money has an end date you can see. Selling is the right route when it does not, or when the cost of the loan over the term you need would exceed the difference between what you would get now and what you would pay to replace the watch later. That comparison is done properly, with the arithmetic, in selling your watch or borrowing against it. Two Rolex-specific points sit on top of it. A current steel sports reference that is hard to buy at retail is often worth more to its owner than its sale price, which argues for pawning. A reference you would happily replace, or one that is due an expensive service, often argues for selling. Buy Your Watch does both, under the same licence, and will tell you which it thinks fits if you ask.
Common mistakes when pawning a Rolex
- Choosing the longest term to be safe. The interest is fixed for the term, so a 12-month loan redeemed in month four still carries twelve months' interest. Pick the term you need.
- Not reading the pawn ticket. It must state the amount, the charge, the period and the description of the watch. If any of those is wrong, fix it before you leave.
- Missing a monthly interest payment. At Buy Your Watch that ends the right to extend. Set the payments up on the day you sign.
- Pawning a watch you do not fully own. A Rolex on finance, or held for a family member, is not yours to pledge.
- Judging the loan on the monthly rate. Ask for the fee, the term and the annual figure together, and for the total repayable on the redemption date.
- Assuming expiry means the watch is gone. It is not gone until it is sold, and you can redeem right up to that point.
- Letting the ticket and the Schedule 3 notice go missing. The ticket is what you redeem with.
If you would rather sell it
Buy Your Watch buys watches valued at $20,000 and above, and a Rolex that would borrow well will usually sell well. Our Submariner selling guide covers the model-level detail for that reference, and where to sell a Rolex in Australia compares the routes. If you sell to us, payment is by Osko bank transfer once your watch has been authenticated by our certified watchmakers, and the entire process takes 24 to 48 hours from submission to payment.
Pawning a Rolex with Buy Your Watch
Founded in Melbourne in 2023, Buy Your Watch Pty Ltd holds second-hand dealer and pawnbroker licence SHD-0017882, issued by Consumer Affairs Victoria, and lends against Rolex and other luxury watches Australia wide. The terms are the ones stated above and on the loan page: a minimum advance of $15,000, 3 to 12 months, a $400 setup fee, 4% to 10% per month, maximum APR 131%, the watch as the only security, no effect on your credit file, insured storage for the term, and the watch back the day the loan is repaid. The full terms, including what happens if the loan is not repaid, are in our terms and conditions and in the agreement you sign before any funds are released.
Pre-pawn checklist
- Reference and serial read and photographed; warranty card, box and service records gathered
- Watch confirmed as yours outright: no finance, not held for anyone else
- Pawnbroker's registration number looked up on the Consumer Affairs Victoria register
- ABN checked and matched to the registered name and the paying account
- Authentication arrangement confirmed: who inspects the watch and whether they are certified
- Storage and insurance confirmed: where, for how much, with whom
- Full cost received in writing: advance, term, fee, monthly rate, annual rate, total repayable, redemption date
- Term chosen for the period actually needed, knowing the interest is fixed for it
- Pawn ticket checked item by item against the agreement before leaving
- Notice of charges and the "What are my rights when I pawn goods?" notice received and kept
- Monthly interest payments set up for the due dates
- Redemption date in the diary, with a reminder a month before
This is general information, not legal or financial advice. Where it states a legal position it names the statute, regulation or section, checked against the primary sources and Consumer Affairs Victoria's guidance on 15 September 2026. Cost figures are Buy Your Watch's published terms on the same date.
Frequently Asked Questions
Can I pawn a Rolex without box and papers?
Yes. The warranty card, box and service records raise what the watch would realise at sale and therefore what can be advanced against it, so a watch-only Rolex borrows against a lower figure, but it can still be pawned. The pawnbroker will authenticate the watch itself either way.
How much can I borrow against a Rolex?
A proportion of what the pawnbroker judges the watch would fetch if it had to be sold at the best price reasonably obtainable, less the cost of selling it. That depends on the reference, its condition and the documents with it, so no honest figure can be given without seeing the watch. Buy Your Watch's minimum advance is $15,000, which means the Rolex needs to be one that would clearly realise well above that at sale.
Do I still own my Rolex while it is pawned?
Yes. A pawn loan is a loan secured on the watch, not a sale. Ownership stays with you for the whole term, and the pawnbroker cannot keep the watch if the loan is not repaid: the Second-Hand Dealers and Pawnbrokers Act 1989 (Vic) requires an unredeemed watch to be offered for sale at the best price reasonably obtainable, and section 23A gives you 12 months after the sale to claim any surplus over the debt.
What does it cost to pawn a Rolex in Australia?
At Buy Your Watch: a minimum advance of $15,000 over terms of 3 to 12 months, a $400 setup fee covering authentication and insured storage, interest of 4% to 10% per month depending on assessment, and a maximum annual percentage rate of 131%. Representative example: $15,000 over 3 months at 4% per month with the $400 fee, approximately $17,200 to redeem, an APR of approximately 59%. Interest is fixed for the term and paid monthly.
Does pawning a Rolex affect my credit score?
No. A pawn loan is not reported to a credit reporting body, the assessment has no effect on your credit file, and because the watch is the pawnbroker's only recourse there is no debt to pursue or record if the loan is not repaid.
Can I get my Rolex back after the loan period ends?
Yes, right up until the watch is actually sold. Victorian law allows redemption at any time after the seven-day minimum holding period and before the pawnbroker sells the goods, including after the loan period has expired, on production of the pawn ticket and proof of identity and payment of what is outstanding. Buy Your Watch's agreements also allow extension one month at a time, provided every monthly interest payment has been made when due.
What happens if I cannot repay the loan on my Rolex?
Once the loan period expires and is not extended, the pawnbroker must offer the watch for sale as soon as practicable at the best price reasonably obtainable. The sale settles the debt whatever the watch fetches: Buy Your Watch does not pursue you for any shortfall and your credit file is not affected. If the watch sells for more than the loan plus the reasonable costs of sale, the pawnbroker must notify you within 14 days and you have 12 months to claim the difference under section 23A.
What must a pawn ticket show?
Under Consumer Affairs Victoria's guidance the ticket must show the pawnbroker's name and address, your full name and address, the date of the loan, the amount loaned, a description of the goods, the number of the transaction, the pawnbroker's charge, the period of the loan, and the amounts paid and dates of payment, updated with each payment. You must also be given a written notice of the charges and the prescribed notice on your rights.
Is pawning a Rolex better than selling it?
It depends on whether you want the watch back and whether the need for money has an end date. Borrowing suits a defined period and a watch you would struggle to replace; selling suits an open-ended need or a watch you would happily replace. Our guide to selling your watch or borrowing against it does the arithmetic. Buy Your Watch does both under the same licence.
How long does it take to pawn a Rolex with Buy Your Watch?
Funds are released once the watch has been authenticated by our certified watchmakers, and the process takes 24 to 48 hours from submission to payment. Your rate, term, redemption date and total repayable are confirmed in writing before any funds are released, and you are under no obligation to proceed.
Sources and references
- Second-Hand Dealers and Pawnbrokers Act 1989 (Vic), AustLII
- Second-Hand Dealers and Pawnbrokers Act 1989 (Vic), s 5: second-hand dealers and pawnbrokers to be registered, AustLII
- Second-Hand Dealers and Pawnbrokers Act 1989 (Vic), s 19: identifying persons selling or pawning goods, AustLII
- Second-Hand Dealers and Pawnbrokers Act 1989 (Vic), s 23A: return of residual equity in unredeemed goods that are sold, AustLII
- Second-Hand Dealers and Pawnbrokers (General, Exemption and Record-Keeping) Regulations 2018 (Vic), reg 24: sale of unredeemed goods, AustLII
- Signs, notices and pawn tickets: second-hand dealer and pawnbroker obligations, Consumer Affairs Victoria
- Loan period, storage, disposal and redemption of goods, Consumer Affairs Victoria
- Keeping records: second-hand dealer and pawnbroker obligations, Consumer Affairs Victoria
- National Consumer Credit Protection Act 2009 (Cth), Schedule 1, National Credit Code (ss 6(9), 32A, 76 to 81), AustLII